
Sectors / Technology
We don’t just know tech. We are tech.
We’ve built and sold tech businesses ourselves. And we bring a global tech M&A team to back you the rest of the way.
Watch
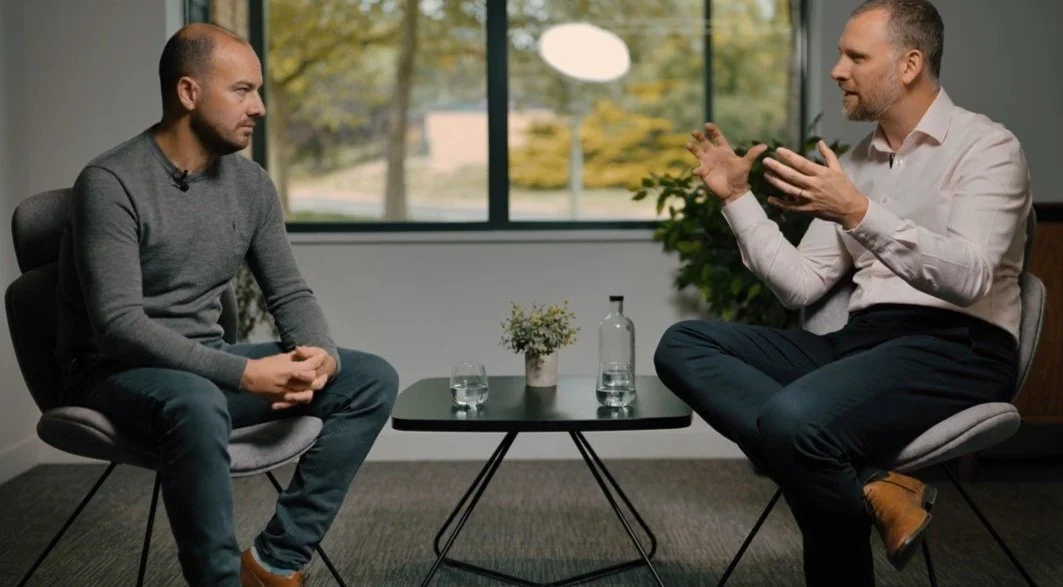
Richard and Simon on technology M&A
Why we focus on technology, what acquirers are paying for, and how we run a process in this market.
Watch the full version →
Where we work in technology
MSPs, cloud and cyber. Contract quality and churn drive the multiple.
SaaS and licensed software, where ARR, retention and margin are everything.
Connectivity, unified comms and digital agencies consolidating fast.
Recent technology deals


A powerful combination
A traditional adviser brings one of these. We bring both, on every mandate.
Built, ran and exited a managed IT business as founding owner: three acquisitions, then a merger into a PE-backed group and a secondary exit.
He knows the real value drivers in a tech company: recurring revenue quality, technical team capability, client contract stickiness.
Chartered accountant and founding partner, with deep experience across IT services M&A: listed acquirers, overseas buyers and PE investors.
He brings the financial, legal and process rigour that protects value from diligence through to completion mechanics.
UK technology M&A market intelligence
546 UK technology transactions, tracked deal by deal. Who is buying, what they are paying, and where the market is moving.
Getting on for half of UK technology vendors are selling to capital or to an overseas strategic. A domestic-only process leaves value on the table.
The market clusters in the £5m to £25m range. That is founder-owned, adviser-led territory.
A software business with high-margin recurring revenue. Sector specialism and retention are what earn a premium.
546 deals tell you what the market pays. They do not tell you what your business is worth.
We track every UK technology transaction so that when you come to sell, the buyer list, the timing and the number are already known quantities. Let's talk about yours.
Your best buyer may not be in Britain
We are the exclusive UK member of Pandion Partners. Its sector specialists reach acquirers across Europe, the Americas and Asia that you would not find alone.
Our international reach →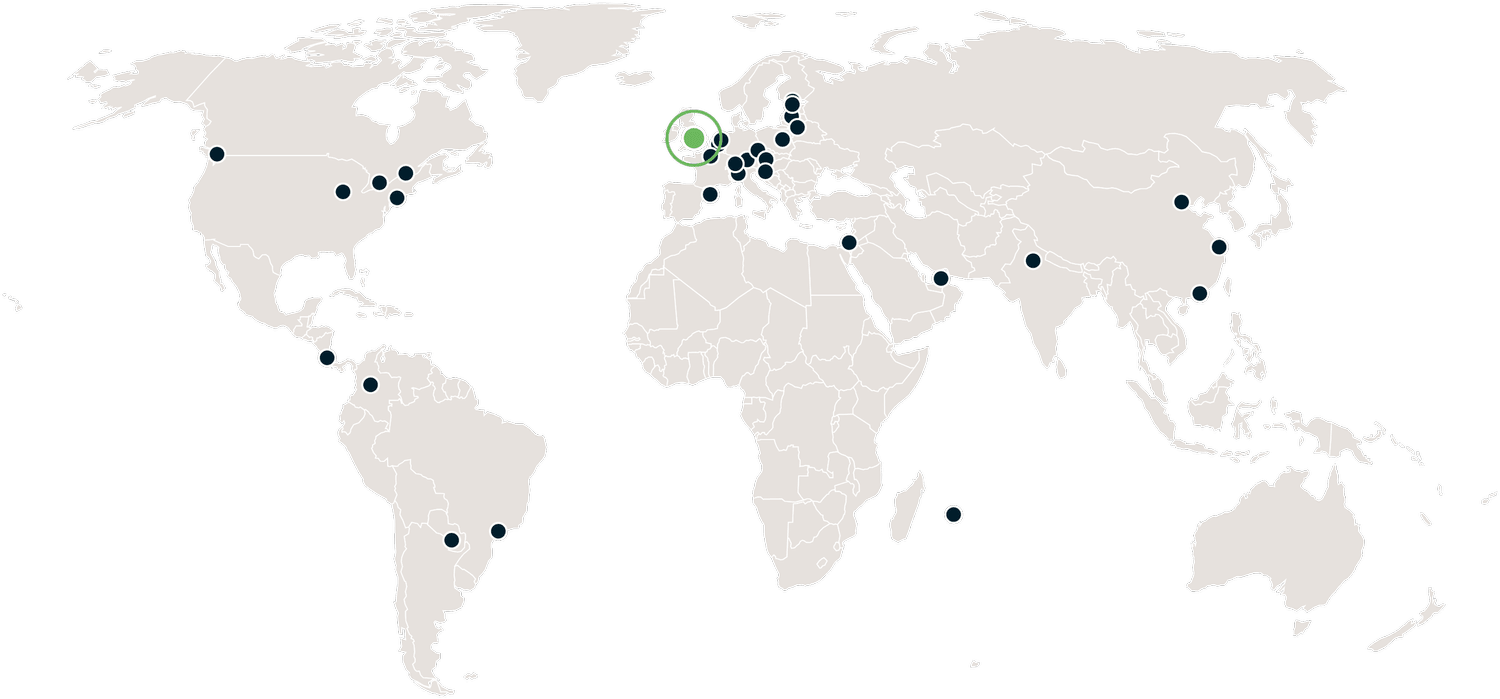
Is your technology ready for sale?
Leave your name and email and we’ll arrange a first call on how to unlock your company’s hidden value and exit potential.